⚠️ This page connects you to Atovia’s partners and affiliate markets. We may receive a commission from affiliate partners for activities made through these links. Discount offers may change at any time according to policy! Rest assured, there are no additional costs to you! We hope this saves you time in finding the right items!
Most insurance claim denials and delays don’t happen because coverage was missing. They happen because of avoidable mistakes: notifying the insurer too late, submitting incomplete paperwork, or filling out the wrong form. This guide walks through the exact process for filing an insurance claim, so you know what to do, what to gather, and what to expect at every stage.
- What Counts as a Valid Insurance Claim
- Step 1: Notify Your Insurer Immediately
- Step 2: Gather Required Documentation
- Step 3: Complete and Submit the Claim Form
- Step 4: Claim Review and Adjuster Assessment
- Step 5: Settlement, Payout, or Denial
- Comparison: Filing Methods
- Common Mistakes That Delay or Deny Claims
- Tips to Speed Up Your Claim Approval
- Frequently Asked Questions
- Notify your insurer as soon as possible after an incident; most policies require prompt notice.
- Document everything before and during the claim: photos, receipts, and any official reports.
- Choose a filing method (online, phone, or agent) that matches how complex your claim is.
- If a claim is denied, you generally have the right to request a review or appeal.
What Counts as a Valid Insurance Claim
An insurance claim is a formal request to your insurer for payment or coverage based on a loss, damage, or event covered under your policy. Before filing, confirm two things: that the event falls within your policy’s coverage terms, and that it occurred while your policy was active. Common claim types include auto (collision, theft), home (damage, theft, liability), health (medical treatment, hospitalization), and life (death benefit). Each type has its own documentation and timeline expectations, but the overall filing process follows the same general steps.
Step 1: Notify Your Insurer Immediately
Contact your insurer as soon as possible after the incident. Many policies include a ‘prompt notice’ requirement, and waiting too long can complicate or even jeopardize your claim, so check your policy document for the specific notification window that applies to you. When you call or log in to report the claim, have the following ready: your policy number, the date and location of the incident, a brief description of what happened, and contact information for anyone else involved. Most insurers offer three ways to report a claim: a mobile app or online portal, a claims phone line, or your agent or broker.
Step 2: Gather Required Documentation
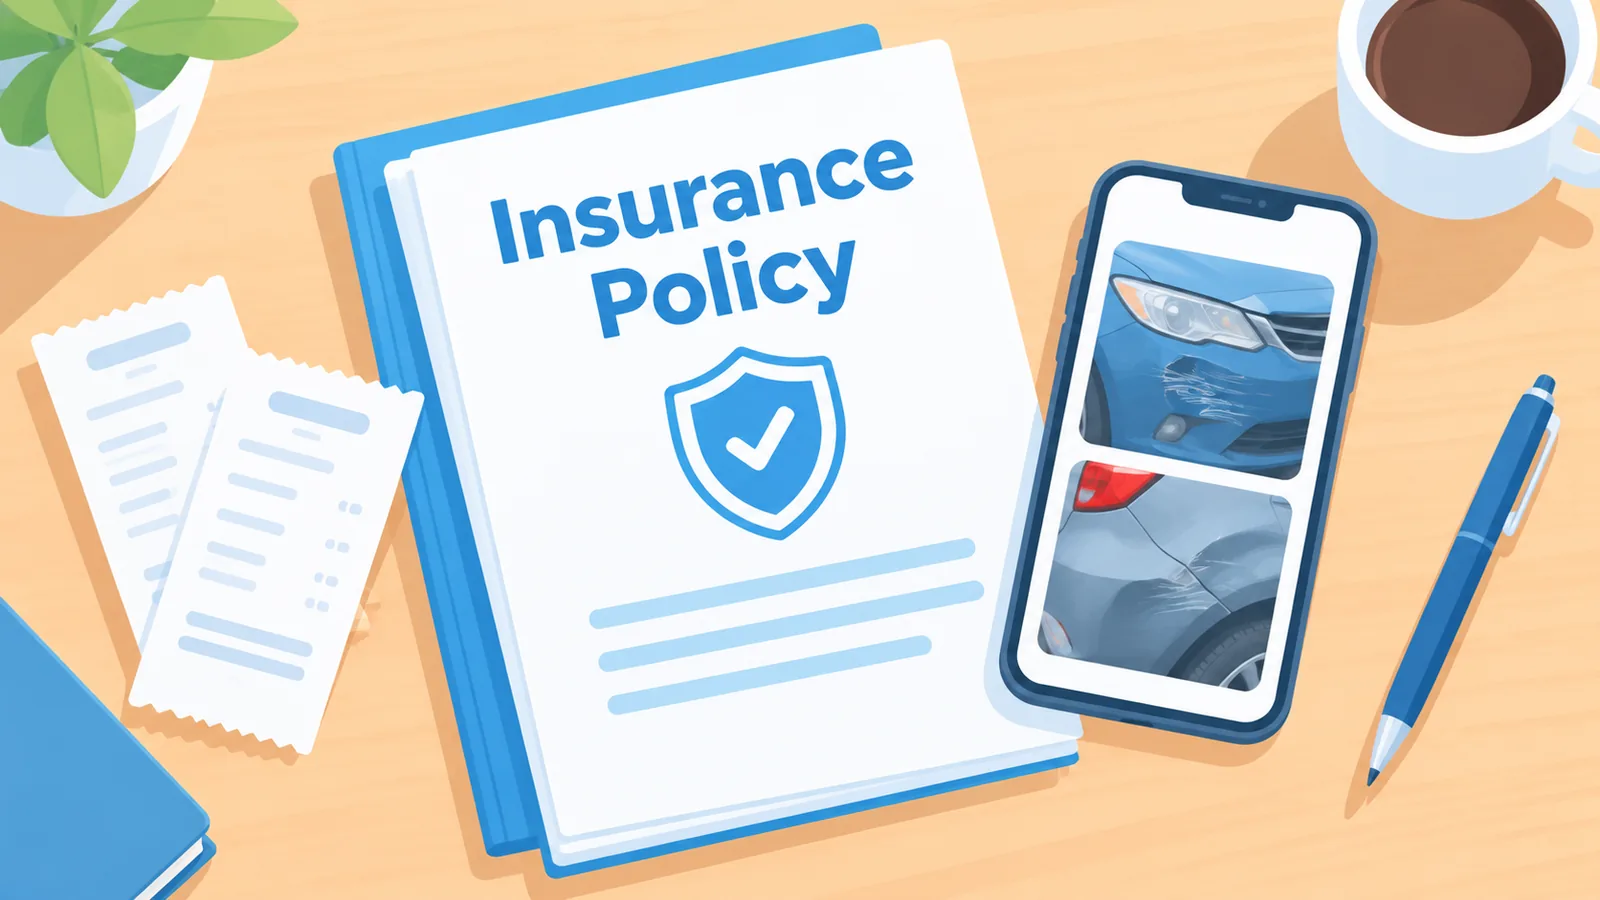
Strong documentation is the single biggest factor in a smooth claim. Before you submit anything, collect:
- Your policy number and a copy of your policy or declarations page
- Government-issued ID
- Clear photos or video of the damage, loss, or scene, taken from multiple angles
- Receipts, invoices, or estimates showing the value of damaged or lost items
- A police report (for theft, auto accidents, or vandalism) or a medical report (for injury or health claims)
- Any correspondence related to the incident, such as witness statements
Common documentation mistakes include submitting blurry or incomplete photos, forgetting to keep copies of receipts, and reporting the incident without noting the exact date and time. Any of these can slow down review or trigger a request for additional information.
Step 3: Complete and Submit the Claim Form
Once you’ve reported the claim and gathered documentation, you’ll complete a claim form either through the insurer’s online portal, over the phone with a representative, or with help from your agent. Fill out every field accurately: mismatched dates, incorrect policy numbers, or vague descriptions of the loss are common reasons claims get sent back for correction. If you’re unsure how to answer a question on the form, contact your insurer or agent directly rather than guessing, since an inaccurate answer can delay processing or affect the outcome.
Step 4: Claim Review and Adjuster Assessment
After submission, your insurer assigns the claim to an adjuster or claims examiner. Their job is to verify that the loss is covered under your policy, review your documentation, and, for property or auto claims, often inspect the damage in person or through submitted photos. Processing time varies significantly depending on the complexity of the claim: straightforward claims with complete documentation are typically reviewed faster than claims involving disputes, large losses, or missing information. During this stage, respond promptly to any requests from the adjuster for additional documents or clarification, since delays on your end extend the overall timeline.
Step 5: Settlement, Payout, or Denial
Once the review is complete, the insurer will issue one of three outcomes: full approval and payout, partial approval, or denial. Payout amounts are generally based on your policy’s coverage limits, any deductible you owe, and the documented value of the loss. If your claim is denied or you disagree with the settlement amount, most insurers have a formal appeal or review process. You can also request a written explanation of the denial, which helps identify whether the issue is missing documentation, a coverage exclusion, or something you can dispute directly with the insurer.
🛒 Recommended Product
| Filing Method | Online Portal | Agent or Broker |
|---|---|---|
| Speed to Report | Fastest, available 24/7 | Depends on agent availability |
| Convenience | High, self-service from any device | Moderate, requires contacting someone |
| Handling Complex Claims | Limited, may need follow-up call | Strong, agent can guide you through details |
| Personal Guidance | Minimal, mostly automated | High, direct human support |
Comparison: Filing Methods
Choosing how to file often comes down to how complex your claim is. A simple, well-documented claim, such as a single item lost or a minor fender bender, is usually fastest through an online portal or app. A more complex claim, such as significant home damage or a disputed liability question, often benefits from the personal guidance an agent or broker can provide, since they can help you avoid errors on the form and explain what documentation the insurer will need.
Common Mistakes That Delay or Deny Claims
- Reporting the incident later than your policy allows
- Submitting incomplete or blurry documentation
- Providing inconsistent details between the initial report and the claim form
- Failing to keep copies of everything you submit
- Not reading the denial letter carefully before deciding whether to appeal
- Letting policy premiums lapse before or during the claims process
Tips to Speed Up Your Claim Approval
- Report the incident the same day it happens whenever possible
- Take more photos than you think you need, from multiple angles and distances
- Keep a written timeline of events, including who you spoke to and when
- Respond to adjuster requests within 24 to 48 hours
- Ask for a claim reference number and use it in all follow-up communication
- Keep digital and physical copies of every document you submit
Frequently Asked Questions
How long does an insurance claim take to process?
Processing time depends heavily on the complexity of the claim and the completeness of your documentation. Simple claims can move quickly, while claims involving disputes or large losses can take considerably longer.
What happens if my claim is denied?
You typically have the right to request a written explanation and to appeal the decision through your insurer’s internal review process. If needed, you can also escalate the matter to your state or regional insurance regulator.
Can I file more than one claim at a time?
Yes, if you experience separate covered events, you can generally file multiple claims. Keep documentation for each claim clearly separated to avoid confusion during review.
How long should I keep claim documentation?
It’s good practice to keep copies of all claim-related documents, including correspondence and receipts, for at least several years after the claim is closed, in case questions arise later.
Do I need a lawyer to file a claim?
Most straightforward claims don’t require legal help. Consider consulting a professional if your claim is denied, disputed, or involves a significant loss where you feel the settlement offer doesn’t match your documented damages.
Want more comparisons and buying guides?
Citing this article
Source: Atovia (Atovia). https://atovia.kr